Inovalis Real Estate Investment Trust Reports Financial Results for the Second Quarter of 2017
/NOT FOR DISTRIBUTION TO U.S. NEWS WIRE SERVICES OR DISSEMINATION IN THE UNITED STATES/
TORONTO, Aug. 9, 2017 /CNW/ - Inovalis Real Estate Investment Trust (the "REIT") (TSX: INO.UN) today reported its financial results for the second quarter of 2017.
HIGHLIGHTS
- Inovalis REIT ("Inovalis REIT", or the "REIT" or "we") is a Canadian REIT managed by Inovalis S.A. ("Inovalis SA"), a local cross-border French and German real estate asset manager, managing $10 billion of real estate and financial assets. As of June 30, 2017, Inovalis SA and Inovalis SA's founding partners had a 13.4% interest in the REIT's equity (directly and indirectly) taking into account a new promissory note from the recent private placement and 14,2% interest excluding the new promissory note.
- On June 26, 2017, the REIT closed a $13.7 million private placement pursuant to the issuance of a Euro denominated promissory note by a subsidiary of the REIT to a single non-Canadian investor for €9.1million paying interest at 8.18%. The Note matures on June 22, 2020. Concurrent with the issuance of the Note, the Investor and the REIT entered into a put/call agreement pursuant to which the REIT can satisfy its obligation to the Investor by delivering REIT units at $10.08 per Unit. At any time after June 25, 2018, the Investor can transfer all or any portion of the Note to the REIT in consideration for REIT units based on the Conversion Price and the REIT can acquire the Note at any time by delivering REIT units to the Investor at the Conversion Price. The Conversion Price represents the market price of the REIT units based on the five-day weighted- average closing price on June 9, 2017.
- On April 13, 2017, the REIT committed €5.3 million ($7.6 million) in a short-term acquisition loan to Aref Diamants Sarl (100%-owned by Inovalis SA) as a first step to the acquisition of Pantin (Paris North-Eastern periphery). The loan generates 9.5% interest income until the acquisition date for the property, which is expected to be closed in Q3 2017. This acquisition is a 50-50 joint-venture with an affiliate of Inovalis SA.
- On June 9, 2017, the REIT acquired a 50% interest in a property located in Stuttgart metropolitan region (Germany), one of the most economically sound and innovative hi-tech regions in Europe and one of the most powerful economic centers in Germany. The property is a 242,832 square feet modern office building with 432 parking units. The property is almost fully let with 96.2% occupancy, and has a weighted average lease term of 6.7 years and has high quality tenants operating in the German automotive industry.
- During the quarter, a new 10-year lease on the entire 124,076 square feet leasable area has been signed in the Hanover property with one of the largest banks in Germany. The bank will take over the lease of the current tenant as of January 1, 2019 and extend the term by five years to 2029. This reflects the demand for the REIT's properties in a strengthening German office market. The new lease has a positive impact on the average term lease which has increased from 5.3 years as at March 31, 2017 to 5.7 years as at June 30, 2017.
- FFO / AFFO
| Q1 2017 (1) |
Q2 2017 (2) |
Q2 2016 (3) |
REIT Guidance (1) (4) |
|
| Including Private Placement equity |
||||
| FFO per unit |
0.19 |
0.20 |
0.20 |
0.21 - 0.23 |
| FFO payout ratio |
111.3% |
104.4% |
104.3% |
90% - 96% |
| AFFO per unit |
0.20 |
0.23 |
0.22 |
0.22 - 0.24 |
| AFFO payout ratio |
105.8% |
91.6% |
88.6% |
88% - 94% |
| (1) $1.4101 C$/€ foreign exchange rate |
||||
| (2) $1.4455 C$/€ foreign exchange rate |
||||
| (3) $1.4842 C$/€ foreign exchange rate |
||||
| (4) $1.4101 C$/€ foreign exchange rate - including future acquisitions and Rueil loan |
||||
In the table above, funds from operations ("FFO") and adjusted funds from operations ("AFFO") for the three-month period ended June 30, 2017 are compared to the Q1 2017, Q2 2016 and the REIT's guidance range.
As at June 30, 2017, proceeds from the $46.0 million equity offering were fully invested but the revenue from the Stuttgart investment only accounted for 21 days in Q2 2017. Despite this gap, the Q2 2017 FFO of $0.20 per unit was in line with the FFO in Q2 2016 and $0.1 higher than Q1 2017 FFO.
AFFO for Q2 2017 of $0.23 per unit was $0.1 higher Q2 2016 FFO and in line with the run rate going forward estimated by the Management. The Q2 2017 FFO payout ratio of 104.4% is almost back to Q2 2016 FFO payout ratio and is expected to reach to the REIT's FFO guidance range in Q3 2017.
The REIT's FFO guidance range is expected to reach $0.21 to $0.23 per Unit and the FFO payout ratio should range between 90% and 96% (the reader is cautioned that this information is forward-looking and actual results may vary from those reported).
The Q2 2017 AFFO payout ratio of $91.5% is slightly higher than the Q2 2016 payout ratio but again on line with the estimated going forward AFFO payout ratio.
- NOI
In the table below, is NOI presentation with the run rate on a same-store basis, including the application of 2017 forecast indexation for French assets. Also presented is the run rate going forward, which includes new acquisitions and fully drown down Rueil loan.
Indexation has not been applied to the German asset forecast as it is not applied until index increases exceed 5%. Between 2013 and 2016, on average, the German index increased 0.50% per year. Over the last 7 months the index has been increasing at a rate of 1.7% per year, indicating an accelerating trend. If this trend continues, the indexation threshold of 5% could be reached between 2018 and 2021 at which time it will be applied to the German assets. These calculations include consideration of the contractual specificities of each lease.
See the section Rental Indexation for details on French and German indices.
| Q1 2017 (1) |
Q2 2017 (2) |
Run rate same |
Q2 2017 same |
REIT Guidance (5) |
|
| NOI (excluding IFRIC 21 impact) |
7,177 |
7,697 |
7,325 |
7,585 |
7,900 - 8,400 |
| 7% |
2% |
6% |
7% - 14% |
||
| NOI & revenue from Rueil acquisition loan |
8,500 - 9,000 |
||||
| 16% - 23% |
|||||
| (1) |
$1.4101 C$/€ foreign and exchange rate |
| (2) |
$1.4455 C$/€ foreign exchange rate & including Stuttgart Q2 2017 revenue |
| (3) |
$1.4101 C$/€ foreign exchange rate |
| (4) |
$1.4455 C$/€ foreign exchange rate & excluding Stuttgart Q2 2017 revenue |
| (5) |
$1.4101 C$/€ foreign exchange rate & including future acquisitions |
The NOI Q2 2017 same store basis increased by 6% including a positive foreign exchange effect, compared to Q1 2017 NOI, which is 4% higher than REIT's estimated same store run rate. The run rate going forward is expected to increase by 7 % to 14% as a result of future acquisitions and by 16% to 23% including Reuil loan revenue. The reader is cautioned that this information is forward-looking and actual results may vary from those reported).
- The REIT's debt to book value was 50.5% as at June 30, 2017, significantly lower than 56.6%, one year ago. Net of cash available, the debt to book value was 48.2% as at June 30, 2017, compared to 55.8% one year before.
Management's discussion and analysis
(Dollar amounts in the MD&A are presented in thousands of Canadian dollars, except rental rates, Unit or as otherwise stated)
OVERVIEW
The presentation of our operational information, financing information and operating results takes into account our proportionate share of income from investments in joint ventures. Please refer to "Non IFRS Reconciliation" for a reconciliation to our condensed interim consolidated financial statements.
| June 30, 2017 |
December 31, 2016 |
||||
| Operational information (1) |
|||||
| Number of properties |
12 |
11 |
|||
| Gross leasable area (sq.ft) |
1,172,139 |
1,050,336 |
|||
| Occupancy rate (end of period) (2) |
96.2% |
95.9% |
|||
| Weighted average lease term |
5.7 years |
5.3 years |
|||
| Average capitalization rate (3) |
5.6% |
5.9% |
|||
| Financing information (1) |
|||||
| Level of debt (debt-to-book value) (4) |
50.5% |
51.3% |
|||
| Level of debt (debt-to-book value, net of cash) (4) |
48.2% |
47.5% |
|||
| Weighted average term of principal repayments of debt |
6.6 years |
7.2 years |
|||
| Weighted average interest rate (5) |
2.06% |
2.11% |
|||
| Interest coverage ratio (6) |
3.9 x |
4.4 x |
|||
| Three months ended |
Six months ended |
||||
| (thousands of CAD$ except per Unit and other data) |
June 30, 2017 |
June 30, 2016 |
June 30, 2017 |
June 30, 2016 |
|
| Operating results |
|||||
| Rental income (1) |
8,100 |
7,797 |
15,672 |
15,231 |
|
| Net rental earnings (1) |
8,522 |
8,349 |
12,893 |
12,501 |
|
| Earnings for the period |
159 |
3,839 |
3,300 |
8,467 |
|
| Funds from Operations (FFO) (7) (8) |
4,647 |
3,648 |
8,981 |
7,403 |
|
| Adjusted Funds from Operations (AFFO) (7) (8) |
5,300 |
4,009 |
9,759 |
8,141 |
|
| FFO per Unit (diluted) (7) (8) |
0.20 |
0.20 |
0.38 |
0.41 |
|
| AFFO per Unit (diluted) (7) (8) |
0.23 |
0.22 |
0.42 |
0.45 |
|
| Distributions |
|||||
| Declared distributions on Units and Exchangeable sec. |
4,852 |
3,805 |
9,675 |
7,427 |
|
| Declared distribution per Unit (diluted) (8) |
0.21 |
0.21 |
0.41 |
0.41 |
|
| FFO payout ratio (7) |
104.4% |
104.3% |
107.7% |
100.3% |
|
| AFFO payout ratio (7) |
91.6% |
93.2% |
99.1% |
90.3% |
|
| (1) |
Taking into account the interest the REIT has in the properties held in partnerships. |
| (2) |
Calculated on weighted areas (activity, storage and intercompany restaurant areas being accounted for only a third of their effective areas). |
| (3) |
Calculated on annualized net rental earnings (based on net rental earnings for the year-to-date period). |
| (4) |
The definition of debt-to-book value and of debt-to-book value, net of cash can be found under the section Non-IFRS Financial Measures. |
| (5) |
Calculated as the weighted average interest rate paid on the finance leases and the mortgage loans. |
| (6) |
Calculated as net rental earnings plus interest, less general and administrative expenses, divided by interest expense on the financial leases and mortgage financings. |
| (7) |
The reconciliation of FFO and AFFO to earnings can be found under the section Non-IFRS Reconciliation (FFO and AFFO). |
| (8) |
Based on the fully diluted weighted average number of Units during the period. |
BASIS OF PRESENTATION
The following management's discussion and analysis ("MD&A") of the financial condition and results of operations of Inovalis REIT should be read in conjunction with the REIT's condensed interim consolidated financial statements for the period from January 1, 2017 to June 30, 2017, and the notes thereto. This MD&A has been prepared taking into account material transactions and events up to and including August 8, 2017. Financial data provided in the condensed interim consolidated financial statements have been prepared in accordance with International Financial Reporting Standards. All amounts in this MD&A are in thousands of Canadian dollars, except per unit amounts and where otherwise stated. Historical results, including trends which might appear, should not be taken as indicative of future operations or results. Additional information about Inovalis REIT has been filed with applicable Canadian securities regulatory authorities and is available at www.sedar.com. The exchange rate used throughout this MD&A for statement of earnings items is the average rate during the said period, i.e. 1.4455 Canadian dollars per Euro for the three-month period ended June 30, 2017. For balance sheet items, projections or market data, the exchange rate used is 1.4813 (exchange rate as at June 30, 2017).
FORWARD-LOOKING INFORMATION
Although we believe that the expectations reflected in the forward-looking information are reasonable, we can give no assurance that these expectations will prove to have been correct, and since forward-looking information inherently involves risks and uncertainties, undue reliance should not be placed on such information. Certain material factors or assumptions are applied in making forward-looking statements and actual results may differ materially from those expressed or implied in such forward-looking statements. The estimates and assumptions, which may prove to be incorrect, include, but are not limited to, the various assumptions set forth in this document as well as the following: (i) we will continue to receive financing on acceptable terms; (ii) our future level of indebtedness and our future growth potential will remain consistent with our current expectations; (iii) there will be no changes to tax laws adversely affecting our financing capability, operations, activities, structure or distributions; (iv) we will retain and continue to attract qualified and knowledgeable personnel as we expand our portfolio and business; (v) the impact of the current economic climate and the current global financial conditions on our operations, including our financing capability and asset value, will remain consistent with our current expectations; (vi) there will be no material changes to government and environmental regulations adversely affecting our operations; (vii) conditions in the international and, in particular, the French and German real estate markets, including competition for acquisitions, will be consistent with the current climate; and (viii) capital markets will provide us with readily available access to equity and/or debt financing.
The forward-looking statements are subject to inherent uncertainties and risks, including, but not limited to, the factors listed under the Risk and Uncertainties section of this MD&A. Consequently, actual results and events may vary significantly from those included in, contemplated or implied by such statements.
MARKET AND INDUSTRY DATA
This MD&A includes market and industry data and forecasts that were obtained from third-party sources, industry publications and publicly available information as well as industry data prepared by Inovalis SA on the basis of its knowledge of the commercial real estate industry in which we operate (including Inovalis SA estimates and assumptions relating to the industry based on that knowledge). Inovalis SA's knowledge of the real estate industry has been developed through its 20 years of experience and participation in the industry. Inovalis SA believes that its industry data is accurate and that its estimates and assumptions are reasonable, but there can be no assurance as to the accuracy or completeness of this data. Third-party sources generally state that the information contained therein has been obtained from sources believed to be reliable, but there can be no assurance as to the accuracy or completeness of included information. Although Inovalis SA believes it to be reliable, Inovalis SA has not verified any of the data from third-party sources referred to in this MD&A, or analyzed or verified the underlying studies or surveys relied upon or referred to by such sources, or ascertained the underlying assumptions relied upon by such sources.
NON-IFRS FINANCIAL MEASURES
Funds from Operations and Adjusted Funds from Operations
FFO and AFFO are not measures recognized under IFRS and do not have standardized meanings prescribed by IFRS. FFO and AFFO are supplemental measures of performance for real estate businesses. We believe that AFFO is an important measure of economic performance and is indicative of our ability to pay distributions, while FFO is an important measure of operating performance and the performance of real estate properties. The IFRS measurement most directly comparable to FFO and AFFO is net earnings. See the Non-IFRS Reconciliation (FFO and AFFO) section for reconciliation of FFO and AFFO to net earnings.
FFO is defined as net earnings in accordance with IFRS, excluding: (i) acquisition costs, (ii) gain on bargain purchase, (iii) net change in fair value of investment properties, (iv) net change in fair value of financial instruments at fair value through profit and loss, (v) changes in fair value of Exchangeable securities, (vi) adjustment for property taxes accounted for under IFRIC 21 (if any), (vii) loss on exercise of lease option, (viii) adjustment for foreign exchange gains or losses on monetary items not forming part of an investment in a foreign operation, (ix) gain on disposal of an interest in a subsidiary and the non-cash portion of earnings from investments accounted for using the equity method, * finance income earned from loans to joint-ventures, (xi) non-recurring finance costs, (xii) deferred taxes and (xiii) gains or losses from non-recurring items. It has also been adjusted to exclude the distributions declared on Exchangeable securities and on Private placement promissory note. These distributions are recognized in profit and loss consistent with the classification of the Exchangeable securities as a liability. However, they are not to be considered when determining distributions for the Unitholders as indeed they are subordinated to the distributions to the Unitholders.
AFFO is defined as FFO subject to certain adjustments, including adjustments for: (i) the non-cash effect of straight line rents, (ii) the cash effect of the lease equalization loans (equalizing the rent payments, providing the REIT with stable and predictable monthly cash flows over the term of the France Telecom leases in the Vanves property, the Smart & Co. lease in the Courbevoie property and the Rue du Commerce leases in the Baldi property (iii) amortization of fair value adjustment on assumed debt, (iv) the non-cash portion of the asset management fees paid in Exchangeable securities, (v) capital expenditures, including those paid by the vendors of the leasehold interest in the properties and/or tenants and (vi) amortization of transaction costs on mortgage loans.
FFO and AFFO should not be construed as alternatives to net earnings or cash flow from operating activities, determined in accordance with IFRS, as indicators of our performance. Our method of calculating FFO and AFFO may differ from other issuers' methods and accordingly may not be comparable to measures used by them.
Debt-to-book value
Our debt-to-book value ratio is calculated on a look-through basis and takes into account the REIT apportioned amount of indebtedness at the partnership level. Indebtedness at the REIT level, as well as at the different partnership levels is calculated as the sum of (i) finance lease liabilities, (ii) mortgage loans, (iii) lease equalization loans, (iv) other long-term liabilities and (v) deferred tax liabilities. Indebtedness does not take into account the contribution from Unitholders that is recorded as a liability, as is the case at the REIT level for the Exchangeable securities, Private placement promissory note and at the partnership level for the contribution from the REIT and its partners.
BUSINESS OVERVIEW AND STRATEGY
Inovalis REIT is an unincorporated open-ended real estate investment trust governed by the laws of the Province of Ontario. Inovalis REIT was founded and sponsored by Inovalis SA, our asset manager. Our Units have been listed on the Toronto Stock Exchange under the trading symbol INO.UN since April 10, 2013. Our head and registered office is located at 151 Yonge Street, 11th floor, Toronto, Ontario, M5C 2W7.
Our long-term objectives are to:
- generate predictable and growing cash distributions on a tax-efficient basis from investments in income-producing office properties;
- maximize the long-term value of both our properties and Units through active and efficient management;
- grow our asset base, primarily in France and Germany, but also opportunistically in other European countries where assets meet our investment criteria; and
- increase the cash available for distribution to holders of Units ("Unitholders"), through an accretive acquisition program that successfully leverages Inovalis SA's extensive relationships and depth of commercial property and financing.
The REIT's Investment criteria encompasses office properties outside of Canada with an occupancy level above 80% (unless AFFO accretive), secured rental cash flows, a property value between €20 million ($28 million) to €60 million ($85 million) (unless AFFO accretive) and a potential future upside with respect to matters including rent and area development. According to management, the target investment size falls within a very liquid segment of the real estate market in Europe, and debt financing for such acquisitions is readily available from local lenders.
BUSINESS ENVIRONMENT
French commercial real estate investment market (1)
The timing of the French presidential elections and the possibility of a "Frexit" appear to have slowed the French investment market in the first half of 2017. While demand remains strong, it is facing a genuine lack of opportunities in the small and medium space segments. Conversely, there is currently a good level of product in the over €200 million segment. Many of these assets should change hands over the second half of 2017 leading to a sharp rise in activity. We therefore expect the full-year investment volume for the Greater Paris Region to stand at €18 billion.
(1) Source: JLL)
Greater Paris Region commercial real estate investment market (1)
Over the last three months, €2.5 billion was invested in the Greater Paris Region investment market; this is slightly higher than the volume recorded over Q1. A total of €5 billion was invested over the first half of 2017 as a whole, this represents a 27% decrease compared with the first half of 2016, but is still in line with the long-term average.
This decline has been seen across all market segments, although to varying degrees. These range from -4% in the €100 to €300 million segment to -30% for transactions from €50 to €100 million. There has been an absence of mega-deals in the major transactions segment over the first half of 2017. While the number of transactions for lot sizes over €100 million remained unchanged year on year (14), this segment only secured €2.5 billion in investments over the first half of 2017, compared with €3.4 billion over the same period last year (-27%). All segments combined, the number of transactions posted a year-on-year decrease with 116 transactions recorded over the last six months, compared with 148 over H1 2016. The average lot size also posted a decrease from €46 to €43 million.
After an optimisticstart to the year (~663,000 sq m), Q2 results for the Greater Paris Region rental market were more subdued (500,000 sq m). This takes the overall figure for the first half of 2017 to 1,164,600 sq m (+4% year on year). Twenty transactions for spaces over 5,000 sq m were carried out over Q1, whereas only 8 were recorded over Q2. Immediate supply remained at around 3.5 million sq m at the end of June with a vacancy rate of 6.7%. Paris is currently suffering from a lack of supply with an average vacancy rate of close to 3%. There was no change in prime asking rents which stood at €760 in the Central Business District and €505 in La Défense
(1) Source: JLL)
German commercial real estate investment market (2)
Investors continue to focus on Germany. An increase in international capital on the market with ongoing strong activity from German investors as well has been recorded since year-start. Approximately €25.9bn was invested in German commercial assets during the first half of 2017. This result reflects an almost 45% increase in transaction volume compared to mid-year 2016, almost setting a new record for half-year activity with 2007 still holding the current record at roughly €28bn. 2017's mid-year result managed to top the 10-year average by a 76%.
Looking at recent developments in numbers, the volume generated by deals involving foreign investors almost doubled to €12bn compared to mid-year 2016, reflecting a 46% share in total transaction volume. German investors, who dominated the market in 2016, remained active as well, increasing their share in transaction volume by 20% to €14bn, a 54% market share.
Investors are still willing to pay increasingly higher purchase prices, as can be seen in the prime yields for office assets in some BIG 7 markets. Even in Frankfurt, yields are now below 4%. The market has even seen a prime property change hands at 30x annual rent. As a result of high rent increases, property owners in Berlin have also been asking higher prices and the city has reached a new record low yield of 3.25%, as has Munich.
(2) Source Colliers
REAL ESTATE MANAGEMENT AND ADVISORY SERVICES
Pursuant to a management agreement, Inovalis SA is the manager of the REIT and provides the strategic, advisory, asset management, project management, construction management, property management and administrative services necessary to manage the operations of the REIT.
Upon the earlier of (i) the REIT achieving a market capitalization of $750 million (including any Exchangeable securities held by Inovalis SA) based on the volume weighted average price (VWAP) over a 20-day trading period and (ii) April 10, 2018, the Management Agreement will terminate and the management of the REIT will be internalized at no additional cost. In anticipation of the term end of the Management Agreement, the independent members of the Board of Trustees have formed a committee to review alternatives available to the REIT.
OUR OPERATIONS
Performance indicators (1)
| As at |
June 30, 2017 |
December 31, 2016 |
||
| Gross leasable area (sq.ft) |
1,172,139 |
1,050,336 |
||
| Number of properties |
12 |
11 |
||
| Number of tenants |
49 |
42 |
||
| Occupancy rate (2) |
96.2% |
95.9% |
||
| Occupancy rate (including Vendor Leases) |
94.7% |
94.3% |
||
| Weighted average lease term (3) |
5.7 years |
5.3 years |
| (1) |
Taking into account the interest the REIT has in the properties held in partnerships. |
| (2) |
Calculated on weighted areas (activity, storage and intercompany restaurant areas being accounted only for a third of their effective areas). |
| (3) |
Excluding early termination rights. Taking into account early termination rights, the weighted average lease term is 4.0 years as at June 30, 2017 compared to 3.5 years as at December 31, 2016. |
Portfolio
The REIT has an interest in 12 properties, of which 7 are entirely owned by the REIT (Baldi, Courbevoie, Jeuneurs, Metropolitan, Sablière and Vanves in France, Hanover in Germany) and 5 are held through partnerships with various global institutional funds (Arcueil in France, Bad Homburg, Cologne, Duisburg and Stuttgart in Germany). Seven properties are in France and 5 properties are in Germany.
These performance indicators do not take the following underlying assets into account: (i) forward purchased property in Ingolstadt (expected to be delivered in the first quarter of 2018) (ii) redevelopment loan granted to the property in Rueil (Paris Western periphery) (iii) acquisition loan on the property in Pantin (Paris north eastern periphery).
Occupancy
With acquisition of the 50% interest in Stuttgart property, the REIT's total gross leasable area increased from 1,050,000 square feet to approximately 1,172,000 square feet.
The 96.2% overall weighted average occupancy rate across the portfolio was maintained at June 30, 2017, the same level at March 31, 2017; this is up slightly from 95.9% as at December 31, 2016.
A new 10-year lease has been signed during the quarter in Hanover property with one of the largest banks in Germany that will take over the lease of the current tenant as from 1, effective January 1, 2019. The end of lease date is also extended five years to the end of 2029. This new lease has a positive impact on the average term lease which increased to 5.7 years as at June 30, 2017 from 5.3 years as at March 31, 2017; this compares to 5.3 years as at December 31, 2016. This reflects the demand for the REIT's properties in a robust German office market. The German markets in which the REIT is invested have a vacancy rate of approximately 5% while REIT assets have about 2% weighted average vacancy.
Tenants
The tenant base in the portfolio is well diversified from an industry segment standpoint, with many national and multinational tenants. As at June 30, 2017, the REIT had 49 tenants. Seventy-two percent of 2017 estimated gross rental income is attributable to French public agency tenants, is guaranteed by large German or international banks, or from investment grade corporations or affiliates of investment grade corporations.
The following table shows our five largest tenants, sorted by contribution to gross leasable area (GLA). The GLA shown for these tenants reflects the percentage of ownership that the REIT has in the underlying property.
| Tenant |
Tenant Sector |
GLA |
Weighted Areas |
% of |
||
| Orange (formerly France Telecom) |
Telecommunications |
268,740 |
253,652 |
23.2% |
||
| Daimler AG |
Manufacturer |
218,271 |
100,578 |
9.2% |
||
| Facility Services Hannover GmbH |
Banking / Real estate |
124,076 |
124,076 |
11.4% |
||
| Mitsubishi Hitachi Power Systems Europe GmbH |
Manufacturer |
108,959 |
104,046 |
9.5% |
||
| Rue du Commerce |
E-commerce |
51,926 |
51,926 |
4.8% |
||
| Top 5 tenants |
771,972 |
634,277 |
58.1% |
|||
| Other tenants |
Diversified |
338,218 |
416,139 |
38.1% |
||
| Vacant |
61,949 |
41,830 |
3.8% |
|||
| Total |
1,172,139 |
1,092,246 |
100.0% |
| (1) |
Taking into account the interest the REIT has in the properties held in partnerships |
| (2) |
Activity, storage and intercompany restaurant areas are weighted by being accounted for a third of their effective areas. |
Our largest tenant Orange is rated BBB+/Baa1/BBB+ by S&P/Moody's/Fitch and has leases in two of our properties, the Vanves property and the Arcueil property (held in partnership).
Leasing profile
Lease rollover profile
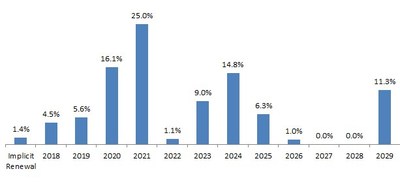
The REIT has an average remaining lease term of 5.7 years (not including tenant early termination rights). Assuming all tenants leave at the earliest possible early termination rights, which is not a likely scenario, the average remaining lease term in our portfolio is 4.0 years. The following graph sets out the amount of GLA and percentage of total GLA of the properties subject to leases expiring during the periods shown (excluding early lease terminations)
Rental indexation
All leases have rental indexation based on the French ICC (construction cost index), ILAT (index averaging construction costs and CPI indexes) or the German Consumer Price Index, as applicable.
CONSOLIDATED FINANCIAL INFORMATION
Our discussion of results of operations includes our proportionate share of income from investments in joint ventures. Please refer to "Non IFRS section" for a reconciliation to our condensed interim consolidated financial statements.
| Three months ended June 30 |
Six months ended June 30 |
|||||
| (in thousands of CAD$) |
2017 |
2016 |
2017 |
2016 |
||
| Rental income |
8,100 |
7,797 |
15,672 |
15,231 |
||
| Service charge income |
1,747 |
1,562 |
3,927 |
3,386 |
||
| Service charge expenses |
(1,476) |
(900) |
(6,669) |
(6,076) |
||
| Other revenue |
(6) |
42 |
80 |
42 |
||
| Other property operating expenses |
(74) |
(152) |
(116) |
(82) |
||
| Net rental earnings |
8,292 |
8,349 |
12,893 |
12,501 |
||
| Administration expenses |
(1,556) |
(1,708) |
(2,997) |
(3,174) |
||
| Foreign exchange (loss) gain |
(62) |
11 |
(62) |
107 |
||
| Net change in fair value of investment properties |
547 |
3,039 |
3,027 |
(222) |
||
| Gain on bargain purchase |
- |
0 |
- |
|||
| Gain resulting from exercice of the purchase option |
- |
(664) |
- |
9,213 |
||
| Acquisition costs |
(1,079) |
(25) |
(1,116) |
(689) |
||
| Operating earnings |
6,142 |
9,002 |
11,746 |
17,736 |
||
| Gain (loss) on financial instruments at fair value through P&L |
(2,343) |
(2,125) |
(1,738) |
(2,369) |
||
| Loss on exercise of early payment option on finance leases |
- |
678 |
- |
(1,242) |
||
| Loss on refinancing of a debt |
- |
- |
- |
(605) |
||
| Finance income |
600 |
2 |
1,157 |
1,168 |
||
| Finance costs |
(1,989) |
(1,947) |
(3,944) |
(4,247) |
||
| Additional income (loss) from Arcueil's JV |
(224) |
1,365 |
(741) |
144 |
||
| Distributions on Exchangeable securities |
(398) |
(482) |
(777) |
(934) |
||
| Net change in fair value of Exchangeable securities |
(1,034) |
(403) |
(1,699) |
(1,019) |
||
| Earnings before income taxes |
754 |
6,090 |
4,004 |
8,632 |
||
| Current income tax expense |
(92) |
(23) |
(126) |
(134) |
||
| Deferred income tax expense |
(448) |
(229) |
(519) |
(74) |
||
| Earnings for the period |
213 |
5,838 |
3,360 |
8,424 |
||
| Non-controlling interest |
55 |
(1) |
60 |
(43) |
||
| Earnings for the period (part attributable to the Trust) |
159 |
5,839 |
3,300 |
8,467 |
||
Net rental earnings
Rental income for the three-month period ended June 30, 2017 was $8,100 compared to $7,797 in Q2 2016. The $303 increase year over year accounted for by a $153 negative foreign exchange impact and a $507 increase of which $115 comes from new acquisitions (Stuttgart property) and $392 derives mainly from new leases on Metropolitan, Vanves and Courvevoie properties.
Rental income for the six-month period ended June 30, 2017 of $15,672 increased by $838 compared to the same period in 2016 of which $730 comes from new acquisitions (Metropolitain and Sttutgart properties) and the balance corresponds mainly to new leases partially offset by the end of the vendor lease on the Vanves property. This increase was partially offset by $397 negative FX impact which results in $441 year on year decrease.
Net rental earnings for the three-month period ended June 30, 2017 was $8,282 compared to $8,349 in Q2 2016. The $161 increase in net rental earnings was offset by $218 negative foreign exchange impact which results in $57 decrease year over.
Net rental earnings for the six-month period ended June 30, 2017 was $12,893 compared to $12,501 in the same period in 2016. The $392 increase takes into account $718 year-over-year increase mainly coming from the acquisition of new properties (Metropolitain and Stuttgart) and new leases on Courbevoie, Vanves, Sablière and Metropolitain properties, offset by a $326 negative foreign exchange impact.
Administration expenses
Administration expenses are primarily comprised of asset management fees paid to Inovalis SA and other general administrative expenses such as trustee fees, directors' and officers' liability insurance, professional fees (including accounting fees), legal fees, filing fees, Unitholder related expenses and other expenses.
Administration expenses for the quarter ended June 30, 2017 amounted to $1,556 vs. $1,708 for the same quarter in 2016. $889 is related to the asset management fees paid to Inovalis SA vs. $846 for the quarter ended June 31, 2016 and $666 to other expenses vs. $862 for the quarter ended June 30, 2016, i.e. 29 % year over year decrease (26% excluding the foreign exchange impact) as a result of management's efforts to contain administrative expenditures. The increase of $43 in asset management fees corresponds to a $22 decrease due to the impact of foreign exchange and a $65 increase corresponding to the Metropolitain and Stuttgart asset acquisitions partially offset by Cologne (the Cologne asset management fees were invoiced after the payment of the acquisition price in May 2016).
Administration expenses for the six-month period ended June 30, 2017 amounted to $2,997 vs. $3,174 for the same period in 2016. $1,727 is related to the asset management fees paid to Inovalis SA vs. $1,600 for the same period in 2016 and $1,269 to other expenses vs. $1,574 for the same period ended June 30, 2016, i.e. 24 % year over year decrease (21% excluding the foreign exchange impact). Other administrative expenses decreased by $305 of which $41 is due to the impact of foreign exchange and $264 to operational efficiencies notwithstanding that the portfolio increased with the Metropolitain and Stuttgart acquisitions. The increase of $127 in asset management fees corresponds to a $42 decrease due to the impact of foreign exchange and an $85 increase corresponding to the Metropolitain and Stuttgart asset acquisitions
Net change in fair value of investment properties
During the quarter ended June 31, 2017, the net change in fair value of investment properties recognized in earnings was a gain of $547 (see section on Property Capital Investment – Fair Value) compared to the $3,039 gain in the quarter ended March 31, 2016 when most of the additional value of this very class of assets, based especially on the nature of building and WALT (weighted average lease term) was already appraised.
Acquisition costs
Acquisition costs of $1,079 for the quarter ended June 30, 2017 and $1,116 for the six-month period ended June 30, 2017 are related to the Stuttgart asset acquisition.
For the three-month and the six-month periods ended June 30, 2016, the acquisition costs were respectively $25 and $689 mainly attached to the Metropolitain acquisition et the Hanover refinancing.
Gain (loss) on financial instruments at fair value through profit and loss
The REIT recognized a gain on financial instruments at fair value through profit and loss for the quarter ended June 30, 2017 of $2,345 vs $2,125 for the same period in 2016. For the six-month period ended June 30, 2017, the REIT recognized a loss of $1,738 vs $2,369 for the period ended June 30, 2017. These losses are mostly the result of the variation in value realized on the foreign exchange contracts.
Loss on exercise of early payment option on finance leases
There was no loss on exercise of the early payment option on finance leases in the quarter ended June 30, 2017. A profit of $678 recorded in Q2 2016 and a loss of $1,242 in the six-month period ended June 30, 2016 are related to the exercise by the REIT of its option to purchase the Metropolitan property that was financed under a finance lease. Concurrently with the transaction, the REIT closed a new finance lease contract to replace the finance lease assumed as part of the transaction.
Loss on debt refinancing
There was no debt refinancing in the quarter ended June 30, 2017. The amount of $605 recorded in the six-month period ended June 30, 2016 is related to the refinancing of the Hanover property's debt. The finance lease in place was terminated and replaced with a mortgage financing.
Finance income
For the three-month period ended June 30, 2017, finance income of $600 consists of $553 in interest on the acquisition loans related to the Rueil and Diamant properties and $47 in revenue from the foreign exchange hedging program.
For the six-month period ended June 30, 2017, finance income of $1,157 consists of $974 in interest on the acquisition loan related to the Rueil property and $183 in revenue from both the foreign exchange hedging program and interest on cash deposit.
Finance income for the six-month period ended June 30, 2016, of $1,168 was mostly comprised of the interest received from the acquisition loan related to the Metropolitain property (reimbursed in Q1 2016).
As at June 30, 2017, the REIT had deployed €12.7 million ($18.4 million) of the €21.7 million ($31.4 million) acquisition and redevelopment loan to a company 80%-owned by Inovalis SA, related to the Rueil property, in the Paris Western periphery. The loan bears an annual interest rate of 8.50% and, upon the eventual sale of the property to a third party, 20% of the profit will accrue the REIT. As at June 30, 2017, the REIT had deployed a total €12.7 million ($18.4 million). The final portion of the loan commitment of €9.0 million ($13.0 million) is expected to be deployed late Q3 or early Q4 of 2017.
On April 13, 2017, the REIT committed €5.3 million ($7.6 million) in a short-term acquisition loan to Aref Diamants Sarl (100%-owned by Inovalis SA) as a first step to the Pantin (Paris North-Eastern periphery). The loan has generated 9.5% interest income until the acquisition date for the property, which is expected to be closed in Q3 2017.
Finance costs
For the three-month period ended June 30, 2017, the finance costs amounted to $1,989 vs $1,947 for the same period in 2016 including $1,465 for interest costs related to finance leases, mortgage loans and the lease equalization loans, $335 of interests related to SWAP contracts and $189 of other finance costs (including amortization of fair value adjustment on finance leases assumed at a discount at the time of a business acquisition, amortization of transaction costs on mortgage loans and other miscellaneous costs).The increase of $42 year to year includes a $51 foreign exchange positive impact.
For the six-months period ended June 30, 2017, the finance costs amounted to $3,944 vs $4,247 for the same period in the previous year including $2,798 of interests costs related to finance leases, mortgage loans, the lease equalization loans, $643 of interests related to SWAP contracts and $503 of other finance costs (including amortization of fair value adjustment on finance leases assumed at a discount at the time of a business acquisition, amortization of transaction costs on mortgage loans and other miscellaneous costs). The decrease of $303 was primarily due to the decrease of other finance costs and the positive foreign exchange impact of $111.
Additional income (loss) from Arcueil's JV
For the Arcueil joint venture, the consolidation presentation reflects a 25% proportionate share of results which aligns with the REIT 25% ownership interest. Per the joint venture agreement, and as reflected in the condensed interim consolidated financial statements, the REIT is entitled to receive a 25% share of the net earnings and, upon asset disposal, 75% of the variance of fair value of investment properties, reduced by 100% of foreign exchange derivative costs. This additional loss from Arcueil's joint venture is $(224) for the three-month period ended June 30, 2017 vs $1,365 in Q2 2016 and $(741) for the six-month period ended June 30, 2017 vs $144 in the same period in 2016. The year on year variance is mainly due to the foreign exchange derivative valuation.
Distributions on Exchangeable securities
Distributions to the holders of Exchangeable securities (see note 11 in Consolidated Interim Financial Statements as at June 30, 2017) are calculated in a manner to provide a return that is economically equivalent to the distributions received by the Unitholders. During the three-month period ended June 30, 2017 the distributions recognized on Exchangeable securities were $398 compared to $482 for the same period in 2016. The decrease is accounted for by the conversion by Inovalis S.A. of 920,000 Exchangeable securities into Units in 2016, partially offset by the increase due to the additional Exchangeable securities received by Inovalis SA in lieu of asset management fees.
Net change in fair value of Exchangeable securities
The net change in value of the Exchangeable securities, as well as the cost of distributions recognized on Exchangeable securities, are recognized in profit and loss because, for financial reporting purposes, the Exchangeable securities have been classified as a liability at fair value through profit or loss.
For the three-month period ended June 30, 2017, the REIT reported a loss of $1,034 which is the result of the increase in the amount of the debt ($2,017) resulting from the change of the closing price of the units which was $10.10 on June 30, 2017 compared to $9.54 on March 31, 2017 partially offset by the issuance of $954 of Exchangeable securities in payment of Asset management fees.
For the six-month period ended June 30, 2017 the REIT reported a loss of $1,699 change which is the result of the increase in the amount of the debt ($3,513) resulting from the change of the closing price of the units which was $10.10 on June 30, 2017 compared to $9.18 on December 30, 2016 partially offset by the issuance of $1,808 of Exchangeable securities in payment of Asset Management fees.
Current income tax expense
The current income tax expense of $92 for the quarter ended June 30, 2017 and $92 for the six-month period ended June 30, 2017 is mainly due to a withholding tax paid by the REIT's Luxemburg holding company on the dividends it received from affiliates.
Last 24 Months - Key Financial Information
The information provided in this section includes our proportionate share of income from investments in joint ventures. Please refer to "Non IFRS section" for reconciliation to our condensed interim consolidated financial statements.
| 3-month period ended |
||||||||||
| (in thousands of CAD$) |
June 30, |
March 31, |
Dec. 31, |
Sept. 30, |
June 30, |
March 31, |
Dec. 31, |
Sept. 30, |
||
| Rental income |
8,100 |
7,571 |
8,188 |
7,617 |
7,797 |
7,431 |
6,854 |
6,881 |
||
| Net rental earnings |
8,292 |
4,601 |
8,698 |
7,902 |
8,349 |
4,135 |
6,975 |
6,589 |
||
| Earnings for the period |
159 |
3,141 |
2,984 |
11,833 |
5,839 |
2,628 |
6,641 |
4,479 |
||
| Earnings per Unit (CAD$) |
0.01 |
0.15 |
0.14 |
0.60 |
0.37 |
0.15 |
0.43 |
0.29 |
||
NON-IFRS RECONCILIATION
Investments in joint ventures
The REIT's proportionate share of the financial position and results of operation of its investment in joint ventures, which are accounted for using the equity method under IFRS in the condensed interim consolidated financial statements, are presented below using the proportionate consolidation method (with the exception of Arcueil), which is a non-GAAP measure. For the purpose of the proportionate consolidation, the initial investment of both partners in the joint ventures were considered as being equity investments as opposed to a combination of equity and loans and accordingly, the related proportionate consolidation balance sheet items were eliminated as well as the associated finance income and finance costs.
For the Arcueil joint venture, the consolidation presentation reflects a 25% proportionate share of results which aligns with the REIT 25% ownership interest. Per the joint venture agreement, and as reflected in the condensed interim consolidated financial statements, the REIT is entitled to receive a 75% share of the net profit. A line entitled "additional gain or loss from Arcueil's joint venture" in the consolidated statement of earnings reconciliation to consolidated financial statements bridges both presentations. A reconciliation of the financial position and results of operations to the condensed interim balance sheets and consolidated statements of earnings is included in the tables shown in the Non-IFRS Reconciliation section.
For the three-month period and year ended April 30, 2017, the proportional financial results include the following proportion of the revenues and expenses of each one of the joint ventures: 50% for Duisburg and Walpur (Bad Homburg), 50% of Stuttgart, 49% for Cologne and 25% for Arcueil.
FFO and AFFO
| Three months ended June 30 |
Six Months ended June 30 |
|||||
| (in thousands of CAD$) |
2017 |
2016 |
2017 |
2016 |
||
| Earnings for the period |
159 |
5,839 |
3,300 |
8,467 |
||
| Adjustment to related acquisition costs |
1,079 |
25 |
1,116 |
689 |
||
| Option cost related to the acquisition of the Metropolitan property |
0 |
664 |
0 |
(9,213) |
||
| Loss recognized on exercise of early payment option on finance leases |
0 |
(678) |
0 |
1,242 |
||
| Loss on refinancing of a debt |
0 |
- |
0 |
605 |
||
| Net change in fair value of investment properties |
(547) |
(3,039) |
(3,027) |
178 |
||
| (Gain) loss on financial instruments at fair value through profit and loss |
2,343 |
2,125 |
1,738 |
2,369 |
||
| Adjustment for property taxes accounted for under IFRIC 21 |
(825) |
(930) |
1,781 |
1,752 |
||
| Share of net earnings of investments (equity method) |
0 |
0 |
||||
| Additional income (loss from Arcueil's JV) |
224 |
(1,365) |
741 |
(83) |
||
| Distributions on Exchangeable securities |
398 |
482 |
777 |
934 |
||
| Change in fair value of Exchangeable securities |
1,034 |
403 |
1,699 |
1,019 |
||
| Foreign exchange (loss) gain |
62 |
(11) |
62 |
(107) |
||
| Non-recurring finance income from Inovalis relating to the acquisition loan |
0 |
- |
0 |
(797) |
||
| Other non-recurring finance costs |
216 |
(97) |
216 |
316 |
||
| Deferred income tax expense |
448 |
229 |
519 |
75 |
||
| Minority interest |
55 |
1 |
60 |
(43) |
||
| FFO |
4,647 |
3,648 |
8,981 |
7,403 |
||
| Add/(Deduct): |
||||||
| Non-cash effect of straight line rents |
226 |
(100) |
305 |
223 |
||
| Cash effect of the lease equalization loans |
(190) |
5 |
(426) |
(310) |
||
| Amortization of fair value adjustment on assumed debt |
22 |
48 |
44 |
99 |
||
| Amortization of transaction costs on mortgage loans |
50 |
81 |
91 |
175 |
||
| Non-cash part of asset management fees paid in Exchangeable securities (1) |
445 |
409 |
864 |
697 |
||
| Capex net of cash subsidy |
100 |
(100) |
(100) |
(200) |
||
| Adjustement from investment |
0 |
18 |
0 |
54 |
||
| AFFO |
5,300 |
4,009 |
9,759 |
8,141 |
||
| FFO / Units (diluted) (in CAD$) (2) |
0.20 |
0.20 |
0.38 |
0.41 |
||
| AFFO / Units (diluted) (in CAD$) (2) |
0.23 |
0.22 |
0.42 |
0.45 |
||
| (1) |
For purposes of this presentation, 50% of non-cash part of the asset management fee is included in the AFFO reconciliation. Notwithstanding, 100% of the asset management fee is paid in Exchangeable securities |
| (2) |
Based on the weighted average number of Units (fully diluted), i.e. 23,541,535 and 18,121,533 for the 3-month periods ended June 30, 2017 and June 30, 2016 and 23,448,295 and 17,938,082 for the 6-month periods ended June 30, 2017 and June 30, 2016. |
Management believes FFO is an important measure of our operating performance and is indicative of our ability to pay distributions. However, it does not represent cash flow from operating activities as defined by IFRS and is not necessarily indicative of cash available to fund Inovalis REIT's needs. This non-IFRS measurement is commonly used for assessing real estate performance. Our FFO and AFFO calculations are based on the average foreign exchange rate for the period (1.4455 Canadian dollars per Euro for the period ended June 30, 2017).
Balance sheet reconciliation to consolidated financial statements
| As at June 30, 2017 |
As at December 31, 2016 |
||||||||||
| Assets |
As per REIT's |
Share from |
Proportionate |
As per REIT's |
Share from |
Proportionate |
|||||
| Non-current assets |
|||||||||||
| Investment properties |
431,672 |
133,117 |
564,790 |
412,231 |
97,401 |
509,633 |
|||||
| Investments accounted for using the equity method |
59,381 |
(59,381) |
- |
43,887 |
(43,887) |
- |
|||||
| Acquisition loans and deposit |
28,109 |
- |
28,109 |
8,906 |
- |
8,906 |
|||||
| Derivative financial instruments |
- |
- |
- |
590 |
- |
590 |
|||||
| Total non-current assets |
519,162 |
73,736 |
592,899 |
465,615 |
53,515 |
519,129 |
|||||
| Current assets |
|||||||||||
| Trade and other receivables |
4,332 |
548 |
4,880 |
3,368 |
(35) |
3,333 |
|||||
| Derivative financial instruments |
30 |
159 |
189 |
520 |
152 |
672 |
|||||
| Other current assets |
2,789 |
249 |
3,038 |
1,638 |
375 |
2,013 |
|||||
| Financial current assets |
1,191 |
741 |
1,931 |
27,910 |
- |
27,910 |
|||||
| Cash and cash equivalents |
23,519 |
4,816 |
28,335 |
11,074 |
2,446 |
13,520 |
|||||
| Total current assets |
31,861 |
6,513 |
38,374 |
44,510 |
2,938 |
47,448 |
|||||
| Total assets |
551,023 |
80,249 |
631,272 |
510,125 |
56,452 |
566,577 |
|||||
| Liabilities and Unitholders' equity |
|||||||||||
| Liabilities |
|||||||||||
| Non-current liabilities |
|||||||||||
| Promissory notes |
12,951 |
- |
12,951 |
- |
- |
- |
|||||
| Mortgage loans |
87,607 |
54,256 |
141,864 |
83,998 |
34,547 |
118,545 |
|||||
| Finance lease liabilities |
123,481 |
16,775 |
140,256 |
120,891 |
16,389 |
137,279 |
|||||
| Other long-term liabilities |
- |
1,246 |
1,246 |
- |
947 |
947 |
|||||
| Lease equalization loans |
3,687 |
- |
3,687 |
4,051 |
- |
4,051 |
|||||
| Tenant deposits |
2,165 |
- |
2,165 |
2,178 |
- |
2,178 |
|||||
| Exchangeable securities |
6,024 |
- |
6,024 |
4,603 |
- |
4,603 |
|||||
| Provision on investment (equity method) |
- |
- |
- |
- |
- |
- |
|||||
| Derivative financial instruments |
922 |
171 |
1,093 |
1,616 |
206 |
1,822 |
|||||
| Deferred tax liabilities |
2,567 |
1,633 |
4,200 |
2,236 |
1,273 |
3,509 |
|||||
| Deferred income |
4,487 |
- |
4,487 |
- |
- |
- |
|||||
| Total non-current liabilities |
243,891 |
74,082 |
317,973 |
219,573 |
53,361 |
272,934 |
|||||
| Current liabilities |
|||||||||||
| Promissory notes |
28 |
- |
28 |
- |
- |
- |
|||||
| Mortgage loans |
614 |
66 |
680 |
541 |
- |
541 |
|||||
| Finance lease liabilities |
24,884 |
699 |
25,583 |
24,180 |
637 |
24,816 |
|||||
| Lease equalization loans |
1,235 |
- |
1,235 |
1,184 |
- |
1,184 |
|||||
| Tenant deposits |
294 |
- |
294 |
198 |
- |
198 |
|||||
| Exchangeable securities |
14,087 |
- |
14,087 |
11,995 |
- |
11,995 |
|||||
| Derivative financial instruments |
1,149 |
7 |
1,156 |
1,225 |
6 |
1,231 |
|||||
| Trade and other payables |
9,496 |
4,807 |
14,303 |
7,392 |
2,142 |
9,534 |
|||||
| Other current liabilities |
450 |
484 |
934 |
1,975 |
29 |
2,004 |
|||||
| Deferred income |
5,239 |
105 |
5,344 |
734 |
277 |
1,011 |
|||||
| Total current liabilities |
57,475 |
6,168 |
63,643 |
49,423 |
3,091 |
52,514 |
|||||
| Total liabilities |
301,366 |
80,250 |
381,616 |
268,996 |
56,452 |
325,448 |
|||||
| Equity |
|||||||||||
| Trust units |
189,869 |
- |
189,869 |
189,158 |
- |
189,158 |
|||||
| Retained earnings |
37,857 |
- |
37,857 |
43,455 |
- |
43,455 |
|||||
| Accumulated other comprehensive income |
21,729 |
- |
21,729 |
8,395 |
- |
8,395 |
|||||
| 249,455 |
- |
249,454 |
241,008 |
- |
241,008 |
||||||
| Non-controlling interest |
202 |
- |
202 |
121 |
- |
121 |
|||||
| Total liabilities and equity |
551,023 |
80,250 |
631,273 |
510,125 |
56,452 |
566,577 |
|||||
| (1) Balance sheet amounts presented for the REIT were taken from the interim consolidated financial statements as at June 30, 2017 and audited as at December 31, 2016. |
Consolidated statement of earnings reconciliation to consolidated financial statements
| Three months ended |
||||||||||||
| June 30, 2017 |
June 30, 2016 |
|||||||||||
| (in thousands of CAD$) |
Amounts per |
Share of net |
Total |
Amounts |
Share of |
Total |
||||||
| Rental income |
6,271 |
1,829 |
8,100 |
5,853 |
1,944 |
7,797 |
||||||
| Service charge income |
1,358 |
389 |
1,747 |
1,185 |
377 |
1,562 |
||||||
| Service charge expenses |
(1,165) |
(311) |
(1,476) |
(989) |
89 |
(900) |
||||||
| Other revenue |
219 |
(224) |
(6) |
42 |
- |
42 |
||||||
| Other property operating expenses |
(73) |
- |
(74) |
(26) |
(126) |
(152) |
||||||
| Net rental earnings |
6,610 |
1,683 |
8,292 |
6,065 |
2,284 |
8,349 |
||||||
| Administration expenses |
(1,326) |
(229) |
(1,556) |
(1,505) |
(203) |
(1,708) |
||||||
| Foreign exchange gain |
(62) |
- |
(62) |
11 |
- |
11 |
||||||
| Net change in fair value of investment properties |
(2,181) |
2,728 |
547 |
3,552 |
(513) |
3,039 |
||||||
| Gain resulting from exercice of the purchase option |
- |
- |
- |
(664) |
- |
(664) |
||||||
| Acquisition costs |
- |
(1,079) |
(1,079) |
(30) |
5 |
(25) |
||||||
| Share of profit of an investment (equity method) |
1,114 |
(1,114) |
- |
(153) |
153 |
- |
||||||
| Operating earnings |
4,155 |
1,988 |
6,143 |
7,276 |
1,726 |
9,002 |
||||||
| Gain (loss) on financial instruments at fair value through P&L |
(2,352) |
9 |
(2,343) |
(2,093) |
(32) |
(2,125) |
||||||
| Loss on exercise of early payment option on finance leases |
- |
- |
- |
678 |
- |
678 |
||||||
| Loss on refinancing of a debt |
- |
- |
- |
- |
- |
- |
||||||
| Finance income |
1,524 |
(925) |
600 |
2,784 |
(2,784) |
- |
||||||
| Finance costs |
(1,404) |
(585) |
(2) |
(1,989) |
(1,623) |
(324) |
(2) |
(1,947) |
||||
| Additional income (loss) from Arcueil's JV (3) |
- |
(224) |
(224) |
- |
1,365 |
1,365 |
||||||
| Distributions on Exchangeable securities |
(398) |
- |
(398) |
(482) |
- |
(482) |
||||||
| Net change in fair value of Exchangeable securities |
(1,034) |
- |
(1,034) |
(403) |
- |
(403) |
||||||
| - |
||||||||||||
| Earnings before income taxes |
491 |
263 |
754 |
6,137 |
(47) |
6,090 |
||||||
| Current income tax expense |
(87) |
(5) |
(92) |
(23) |
(23) |
|||||||
| Deferred income tax expense |
(190) |
(258) |
(448) |
(276) |
47 |
(229) |
||||||
| Earnings for the period |
214 |
- |
214 |
5,838 |
- |
5,838 |
||||||
| Non-controlling interest |
55 |
55 |
(1) |
(1) |
||||||||
| Earnings for the period (part attributable to the Trust) |
159 |
- |
159 |
5,839 |
- |
5,839 |
||||||
| (1) |
Income statement amounts presented for the REIT were taken from the interim consolidated financial statements as at June 31, 2017 and June 30, 2016 |
| (2) |
Includes the REIT's share of the hedging cost of Arcueil's partner |
| (3) |
Reflects the additional loss assumed by the REIT in reference to its 75% right to the net profit/loss of the Arcueil joint venture. |
| Six months ended |
||||||||||||
| June 30, 2017 |
June 30, 2016 |
|||||||||||
| (in thousands of CAD$) |
Amounts per |
Share of net |
Total |
Amounts per |
Share of |
Total |
||||||
| Rental income |
12,242 |
3,430 |
15,672 |
11,526 |
3,705 |
15,231 |
||||||
| Service charge income |
3,208 |
719 |
3,927 |
2,775 |
611 |
3,386 |
||||||
| Service charge expenses |
(5,782) |
(887) |
(6,669) |
(5,474) |
(602) |
(6,076) |
||||||
| Other revenue |
303 |
(223) |
80 |
42 |
- |
42 |
||||||
| Other property operating expenses |
(114) |
(2) |
(116) |
(67) |
(15) |
(82) |
||||||
| Net rental earnings |
9,857 |
3,037 |
12,893 |
8,802 |
3,699 |
12,501 |
||||||
| Administration expenses |
(2,572) |
(425) |
(2,997) |
(2,724) |
(450) |
(3,174) |
||||||
| Foreign exchange gain |
(62) |
- |
(62) |
107 |
- |
107 |
||||||
| Net change in fair value of investment properties |
108 |
2,919 |
3,027 |
644 |
(866) |
(222) |
||||||
| Gain resulting from exercice of the purchase option |
- |
- |
- |
9,213 |
- |
9,213 |
||||||
| Acquisition costs |
(37) |
(1,079) |
(1,116) |
(689) |
- |
(689) |
||||||
| Share of profit of an investment (equity method) |
391 |
(391) |
- |
(358) |
358 |
- |
||||||
| Operating earnings |
7,685 |
4,061 |
11,746 |
14,995 |
2,741 |
17,736 |
||||||
| Gain (loss) on financial instruments at fair value through P&L |
(1,781) |
43 |
(1,738) |
(2,237) |
(132) |
(2,369) |
||||||
| Loss on exercise of early payment option on finance leases |
- |
- |
(1,242) |
- |
(1,242) |
|||||||
| Loss on refinancing of a debt |
- |
- |
- |
(605) |
- |
(605) |
||||||
| Finance income |
3,308 |
(2,151) |
1,157 |
2,836 |
(1,668) |
1,168 |
||||||
| Finance costs |
(3,057) |
(887) |
(2) |
(3,944) |
(3,139) |
(1,108) |
(2) |
(4,247) |
||||
| Additional income (loss) from Arcueil's JV (3) |
- |
(777) |
(777) |
- |
144 |
144 |
||||||
| Distributions on Exchangeable securities |
(777) |
36 |
(741) |
(934) |
- |
(934) |
||||||
| Net change in fair value of Exchangeable securities |
(1,698) |
- |
(1,698) |
(1,019) |
- |
(1,019) |
||||||
| 0 |
||||||||||||
| Earnings before income taxes |
3,680 |
325 |
4,005 |
8,655 |
(23) |
8,632 |
||||||
| Current income tax expense |
(97) |
(29) |
(126) |
(108) |
(26) |
(134) |
||||||
| Deferred income tax expense |
(224) |
(295) |
(519) |
(123) |
49 |
(74) |
||||||
| Earnings for the period |
3,359 |
- |
3,360 |
8,424 |
- |
8,424 |
||||||
| Non-controlling interest |
59 |
59 |
(43) |
(43) |
||||||||
| Earnings for the period (part attributable to the Trust) |
3,300 |
- |
3,301 |
8,467 |
- |
8,467 |
||||||
| (4) |
Income statement amounts presented for the REIT were taken from the interim consolidated financial statements as at June 31, 2017 and June 30, 2016 |
| (5) |
Includes the REIT's share of the hedging cost of Arcueil's partner |
| (6) |
Reflects the additional loss assumed by the REIT in reference to its 75% right to the net profit/loss of the Arcueil joint venture. |
PROPERTY CAPITAL INVESTMENTS
Fair value
The fair value of the REIT's investment property portfolio as at June 30, 2017 was $564.8 million including the REIT's interests in the properties held in partnerships (vs. $509.6 million as at December 31, 2016). The fair value of the French properties was $429.4 million (76.0% of total asset value) and the fair value of the German properties was $135.4 million (24.0% of total asset value).
The $55.2 million increase is accounted for by a $26.8 million increase due to Stuttgart asset acquisition, $3.0 million increase in fair value, $0.9 million Capex, $(0.3) rent free impact and $23.2 million increase due to foreign exchange fluctuations.
Management principally uses discounted cash flows to determine the fair value of the investment properties. These values are supported by third party appraisals in conformity with the requirements of the Royal Institution of Chartered Surveyors Standards, and for the French properties also in conformity with the Charte de l'expertise immobilière, European Valuation Standards of TEGoVA (the European Group of Valuers' Association) and IFRS 13.
Please refer to note 4 of the interim consolidated financial statements for a more complete discussion on our investment properties and valuation rates used by the evaluators.
Building improvements
The REIT is committed to improving its operating performance by incurring appropriate capital expenditures in order to replace and maintain the productive capacity of its property portfolio so as to sustain its rental income generating potential over the portfolio's useful life.
Since the IPO in April 2013, a total of $1.7 million has been spent on the properties, funded by a reserve that was set aside by the vendors of the four initial properties. Improvement works of $2.2 million on Courbevoie property begun in Q2 2017 and will be completed in 2017.
Guarantees, commitments and contingencies
The REIT and its subsidiaries have provided guarantees in connection with the finance lease liabilities and the mortgage loans, including pledge of affiliates of the REIT, first mortgages and assignment of receivables and future receivables. As at June 30, 2017, guarantees provided by the REIT with respect to its long-term debts include a preferential claim held by mortgage lenders on the Jeuneurs, Veronese, Sablière and Hanover properties in the amount of $88.4 million. Including the REIT's interest in the properties held in partnerships, preferential claim held by mortgage lenders on the properties totals $142.9 million.
OTHER SIGNIFICANT ASSETS
Investments accounted for using the equity method
This section encompasses the 50% interest the REIT (through its subsidiaries) has in the Duisburg property, the 50% interest in the Walpur property, the 25% interest in the Arcueil property, the 49% interest in the Cologne property and 50% in the Stuttgart property. Our share of fair value of the investment properties accounted for using the equity method was $59,381 as at June, 2017 compared to $43,887 as at December 31, 2016.
Acquisition loans and deposit
As at June 30, 2017, Acquisition loans and deposit of $28.1 million consisted mainly of the $18.9 million loan commitment for the Rueil project, $7.9 loan commitment for Diamant property acquisition and the $1.1 million deposit for the Ingolstadt forward purchase.
Trade and other receivables
Trade and other receivables as at June 31, 2017 amounted to $4,880 taking into account the REIT's interests in the properties held in partnerships compared to $3,333 as at December 31, 2016. The difference of $1,547 corresponds to a $1,396 increase mainly due to the property taxes recognized according to IFRIC 21 rules to be recharged to the tenants in Q4 and to the $151 foreign exchange impact.
Other current Assets
Other current assets as at June 30, 2017 amounted to $3,038 compared to $2,013 as at December 31, 2016. This includes the 50% share of the deposit pertaining to the Ingolstadt forward purchase ($1,111) that will be borne by the yet-to-be chosen partner on this transaction. The balance of other current assets consists mainly of sales tax receivables.
PRESENTATION OF OUR CAPITAL
Liquidity and capital resources
Inovalis REIT's primary sources of capital are cash generated from operating activities, credit facilities, sharing the ownership of actual assets owned entirely and equity issues. Our primary uses of capital include property acquisitions, payment of distributions, costs of attracting and retaining tenants, recurring property maintenance, major property improvements and debt interest payments. We expect to meet all of our ongoing obligations through current cash, cash flows from operations, debt refinancing and, as growth requires and when appropriate, new equity or debt issues. We can also sell some portion of assets owned in order to get access to capital but also in the perspective of diversification of our portfolio.
The REIT's cash available was $23.5 million as at June 30, 2017 compared to $11.1 million as at December 31, 2016. Including the REIT's interest in the joint ventures, cash available totals $28.3 million as at June 30, 2017, compared to $13.5 million as at December 31, 2016. This includes the net proceeds of the $13.1 million ($13.6 million gross proceeds) private placement which closed on June 26, 2017. Gross proceeds from July 2016 equity offering of $46.0 million resulted into net proceeds of $43.1 million after deduction of $2.9 million of offering costs were fully invested as at June 2017 in Rueil and Diamant acquisition loans and Stuttgart property.
Financing activities
Our debt strategy is to have secured mortgage financing with a term to maturity that is appropriate in relation to the lease maturity profile of our portfolio and then to put in place, when appropriate, interest-only financings. We intend to search for fixed rate financings or floating rate financings with a cap. As such, 93.8% of the REIT's senior debt benefits from an interest rate protection (77.5% in the form of a swap and 16.3% in the form a cap). Our preference is to have staggered debt maturities to mitigate interest rate risk and limit refinancing exposure in any particular period. With no financial institution representing more than 30% of our senior debt commitment, we also make sure that the REIT has a diversified base of senior debt providers. Our debt to book value stands at 50.5% and net of the $28.3 million of cash available (including financial current assets) as at June 30, 2017 (including the REIT's interest in the joint ventures), this debt to book value stands at 48.2%.
Key performance indicators in the management of our debt are summarized in the following table, which also takes into account the interests the REIT has in all assets held in partnerships.
| As at June 30, 2017 |
As at December 31, 2016 |
|||
| Weighted average interest rate (1) |
2.06% |
2.11% |
||
| Debt-to-book value (2) |
50.5% |
51.3% |
||
| Debt-to-book value, net of cash (2) |
48.2% |
47.5% |
||
| Interest coverage ratio (3) |
3.9 x |
4.4 x |
||
| Debt due in next 12 months in thousand of CAD$ |
25,498 |
25,357 |
||
| Weighted average term to maturity of debt (4) |
6.6 years |
7.2 years |
| (1) |
Calculated as the weighted average interest rate paid on the finance leases and the mortgage financing. |
| (2) |
The definition of debt-to-book value and of debt-to-book value, net of cash can be found under the section Non-IFRS Financial Measures |
| (3) |
Calculated as net rental earnings plus interest, less general and administrative expenses, divided by interest expense on the financial leases and mortgage financings. |
| (4) |
Calculated as the weighted average term on all the financial leases and mortgage financings. |
Equity
Our discussion about equity is inclusive of Exchangeable securities and Private placement promissory note which are economically equivalent to the REIT's Units. In our consolidated financial statements, the Exchangeable securities are classified as a combination of current and non-current liabilities under IFRS because of the conversion feature that can be exercised by the holder of those securities.
| 3-month period ended |
6-month period ended |
|||
| Units |
||||
| Number at beginning of period |
21,564,572 |
21,525,775 |
||
| Increase/(Decrease) in number during the period |
- |
- |
||
| Units issued pursuant to the DRIP |
40,142 |
78,939 |
||
| Number at end of period |
21,604,714 |
21,604,714 |
||
| Weighted average number during the period |
21,584,020 |
21,564,609 |
||
| Exchangeable securities |
||||
| Number at beginning of period |
1,896,676 |
1,808,051 |
||
| Increase/(Decrease) in number during the period |
94,514 |
183,139 |
||
| Number at end of period |
1,991,190 |
1,991,190 |
||
| Weighted average number during the period |
1,897,715 |
1,853,621 |
||
| Promissory notes |
||||
| Number at beginning of period |
- |
- |
||
| Increase/(Decrease) in number during the period |
1,360,449 |
1,360,449 |
||
| Number at end of period |
1,360,449 |
1,360,449 |
||
| Weighted average number during the period |
59,800 |
30,065 |
||
| Units, Exchangeable securities and Promissory notes |
||||
| Number at beginning of period |
23,461,248 |
23,333,826 |
||
| Increase/(Decrease) in number during the period |
1,495,105 |
1,622,527 |
||
| Number at end of period |
24,956,353 |
24,956,353 |
||
| Weighted average number during the period |
23,541,535 |
23,448,295 |
||
Further to the Distribution Reinvestment Plan ("DRIP"), 40,142 Units were issued to Unitholders during Q2 2017 and a total of 78,939 for the period ended June 30, 2017. As at June 30, 2017, 9.5% of the Units were enrolled in the DRIP.
Distribution and management of foreign exchange risk
Our Declaration of Trust provides our trustees with the discretion to determine the percentage payout of income that would be in the best interests of the REIT. Given that the level of working capital tends to fluctuate over time and should not affect our distribution policy, we do not consider it when determining our distributions.
In order to ensure the predictability of distributions to our Unitholders, we have established an active foreign exchange hedging program. As at June 30, 2017, the REIT was committed to sell €880 (on the average) at an average rate of 1.4819 and to receive $1,300 on a monthly basis until April 2019 (included).
| Three months ended June 30 |
Six months ended June 30 |
|||||||
| (in thousands of CAD$ except for per Unit amounts) |
2017 |
2016 |
2017 |
2016 |
||||
| Declared distributions on Units |
4,454 |
3,264 |
8,898 |
6,493 |
||||
| Declared distributions on Exchangeable securities |
398 |
482 |
777 |
934 |
||||
| Total declared distributions |
4,852 |
3,746 |
9,675 |
7,427 |
||||
| Distribution per Unit (diluted) |
$ 0.20625 |
$ 0.20625 |
$0.41250 |
$0.41250 |
||||
We currently pay monthly distributions to Unitholders of $0.06875 per Unit, or $0.825 per Unit on an annual basis.
ANALYSIS OF DISTRIBUTED CASH
| Three months ended June 30 |
Six months ended June 30 |
|||||||
| 2017 |
2016 |
2017 |
2016 |
|||||
| Cash flows from operating activities (A) |
6,818 |
5,704 |
16,622 |
11,194 |
||||
| Earnings before income taxes (B) |
213 |
5,838 |
3,360 |
8,661 |
||||
| Declared distribution on Units (C) |
4,454 |
3,264 |
8,898 |
6,493 |
||||
| Excess (shortfall) of cash flows from operating activities over |
||||||||
| cash distributions paid (A - C) |
2,364 |
2,440 |
7,724 |
4,701 |
||||
| Excess (shortfall) of profit or loss over cash distributions paid (B - C) |
(4,241) |
2,574 |
(5,538) |
2,168 |
||||
As shown in the table above, the cash flows related to operating activities as reported in the REIT's consolidated statement of cash flows exceeded the cash distributions declared for the period ended June 30, 2017.
The earnings reported during the period are lower than the amount of distributions declared for the period ended June 30, 2017. The shortfall of $4.241 was compensated by the excess cash flow generated in the previous quarters.
Every quarter, the REIT ensures that sufficient funds were being generated from rental operations to continue making distributions at the planned rate. To perform this assessment, management uses the FFO and AFFO measures presented in the section entitled Non-IFRS reconciliation (FFO and AFFO). These measures are used to determine the amount of funds generated by ongoing rental operations that are available for distribution. These measures remove from consideration those gains and losses that are recognized for accounting purposes but that do not impact cash flow. They also remove from consideration various revenues and expenses that are recognized in profit or loss for accounting purposes but which do not arise from ongoing rental operations, for example because they were incurred to acquire revenue generating assets.
As quantified in the FFO and AFFO calculations, the funds used to make the distributions during the current quarter were generated through the REIT's ongoing rental operations.
The REIT expects to continue paying distributions based on the current plan.
RISK AND UNCERTAINTIES
We are exposed to various risks and uncertainties, many of which are beyond our control, the occurrence of which could materially and adversely affect our investments, prospects, cash flows, results of operations or financial condition and our ability to make cash distributions to Unitholders. We believe the risk factors described below are the most material risks that we face, however they are not the only ones. Additional risk factors not presently known to us or that we currently believe are immaterial could also materially and adversely affect our investments, prospects, cash flows, results of operations or financial condition and our ability to make cash distributions to Unitholders and negatively affect the value of the Units.
Risks relating to the REIT and its business
Risks inherent in the real estate industry may adversely affect our financial performance
Real estate ownership is generally subject to numerous factors and risks, including changes in general economic conditions, local economic conditions, the attractiveness of properties to potential tenants or purchasers, competition with other landlords with similar available space, and the ability of the owner to provide adequate maintenance at competitive costs.
The properties generate income through rent payments made by our tenants. Upon the expiry of any lease, there can be no assurance that the lease will be renewed or the tenant replaced for a number of reasons. Furthermore, the terms of any subsequent lease may be less favorable than the existing lease. Our cash flows and financial position would be adversely affected if our tenants were to become unable to meet their obligations under their leases or if a significant amount of available space in our properties could not be leased on economically favorable lease terms. In the event of default by a tenant, we may experience delays or limitations in enforcing our rights as sub-lessor and incur substantial costs in protecting our investment. Furthermore, at any time, a tenant may seek the protection of bankruptcy, insolvency or similar laws, which could result in the rejection and termination of the lease of the tenant and, thereby, cause a reduction in the cash flows available to us.
An investment in real estate is relatively illiquid. Such illiquidity will tend to limit our ability to vary our portfolio promptly in response to changing economic or investment conditions. The costs of holding real estate are considerable and during an economic recession we may be faced with ongoing expenditures with a declining prospect of incoming receipts. In such circumstances, it may be necessary for us to dispose of properties at lower prices in order to generate sufficient cash for operations and making distributions and interest payments.
Concentration of tenants may result in significant vacancies on the Properties
Five of our largest tenants, by percentage of total GLA, occupy approximately 59% of the total weighted areas. Although all five tenants are committed to multi-year leases, which are set to expire gradually between 2020 and 2029, there is no assurance that such tenants will continue to occupy such premises for the remainder of their lease terms. Some of them have indeed break options before the end of their leases, and the soonest dates on which those five largest tenants may effectively move range between 2018 and 2021. In order to minimize this risk of vacancy, Inovalis REIT will continue to closely monitor all leases and ensure that they work with the current tenants to determine their future leasing plans, which would allow Inovalis REIT to source tenants in advance of the current tenants vacating the property.
Lease renewals, rental increases, lease termination rights and other lease matters
Expiries of leases for our properties will occur from time to time over the short and long-term. No assurance can be provided that we will be able to renew any or all of the leases upon their expiration or that rental rate increases will occur or be achieved upon any such renewals. The failure to renew leases or achieve rental rate increases may adversely impact our financial condition and results of operations and decrease the amount of cash available for distribution.
Although certain, but not all, leases contain a provision requiring tenants to maintain continuous occupancy of leased premises, there can be no assurance that such tenants will continue to occupy such premises which may have an adverse effect on us and could adversely impact our financial condition and results of operations and decrease the amount of cash available for distribution. In addition, certain leases contain a provision which gives tenants the right to terminate their leases upon payment of a penalty.
Moreover, pursuant to the lease agreement with the National Conservatory of Arts and Crafts, none of the value-added taxes on expenses legally due by the REIT are recoverable. However, property taxes and office taxes are recoverable. Similarly pursuant to the Fresh & Co. and French Environment and Energy and Management Agency lease agreements, several forms of taxes, including but not limited to, property taxes, household refuse taxes and annual office taxes will be borne by the REIT. As a result, we will bear the economic cost of increases to these taxes.
Head Lease for properties
According to the head leases for certain of the properties, the owners of such properties have certain participation rights with respect to such properties pursuant to which a French dedicated SPV (a "French SPV") or the German SPV, as the case may be, would need to obtain written consent from the respective owner prior to taking certain actions with respect to such property, including cancelling or amending lease agreements for such property. If the owner does not give its prior consent to such actions, it may terminate the applicable head lease.
Environmental contamination on properties may expose us to liability and adversely affect our financial performance
The properties may contain ground contamination, hazardous substances, wartime relics (including potentially unexploded ordnance) and/or other residual pollution and environmental risks. Buildings and their fixtures might contain asbestos or other hazardous substances above the allowable or recommended thresholds, or the buildings could bear other environmental risks. Prior to acquiring the interests in the properties (including the leasehold interests), we undertook environmental studies on each property. No sign of pollution was evidenced on any of the properties.
We are subject to various federal, state and municipal laws relating to environmental matters. Such environmental laws impose actual and contingent liabilities on us to undertake remedial action on contaminated sites and in contaminated buildings. The costs of any removal, investigation or remediation of any residual pollution on such sites or in such buildings as well as costs related to legal proceedings, including potential damages, regarding such matters may be substantial.
We have insurance in place to protect against certain environmental liabilities in respect of certain of the properties, with limits, which are customary and available for portfolios similar to ours.
We make the necessary capital and operating expenditures to ensure compliance with environmental laws and regulations. Although there can be no assurance, we do not believe that costs relating to environmental matters will have a material adverse effect on our investments, financial condition, results of operations or distributions or cash interest payments.
We may incur significant capital expenditures and other fixed costs
Certain significant expenditures must be made throughout the period of ownership of real property, regardless of whether the property is producing sufficient income to pay such expenses. In order to retain desirable rentable space and to generate adequate revenue over the long term, we must maintain or, in some cases, improve each property's condition to meet market demand, which can entail significant costs we may not be able to pass on to our tenants.
Any failure by us to undertake appropriate maintenance and refurbishment work in response to the factors described above could entitle tenants to withhold or reduce rental payments or even to terminate existing letting contracts. Any such event could have a material adverse effect on our cash flows, financial condition and results of operations and our ability to make distributions on the Units.
Financing risks, leverage and restrictive covenants may limit our ability for growth
The real estate industry is capital intensive. We will require access to capital to maintain our properties, as well as to fund our growth strategy and significant capital expenditures from time to time. There is no assurance that capital will be available when needed or on favorable terms. Our failure to access required capital could adversely impact our investments, cash flows, operating results or financial condition, our ability to make distributions on the Units and our ability to implement our growth strategy.
A high level of indebtedness increases the risk that we may default on our debt obligations. Our ability to make scheduled payments of the principal of, or interest on, and to otherwise satisfy our debt obligations depends on future performance, which is subject to the financial performance of our properties, prevailing economic conditions, prevailing interest rate levels, and financial, competitive, business and other factors, many of which are beyond our control.
Changes in government regulations may affect our investment in our properties
We are subject to laws and regulations governing the ownership and leasing of real property, employment standards, environmental and energy efficiency matters, taxes and other matters. It is possible that future changes in applicable federal, state, local or common laws or regulations or changes in their enforcement or regulatory interpretation could result in changes in the legal requirements affecting us (including with retroactive effect). In addition, the political conditions in the jurisdictions in which we operate are also subject to change. Any changes in investment policies or shifts in political attitudes may adversely affect our investments. Any changes in the laws to which we are subject in the jurisdictions in which we operate could materially affect the rights and title to the properties. All of the properties are located in France and Germany. Although the governments in France and Germany are stable and generally friendly to foreign investments, there are still political risks. It is not possible to predict whether there will be any further changes in the regulatory regime(s) to which we are subject or the effect of any such change on our investments.
Failure to receive deductions for interest payments may adversely affect our cash flows, results of operations and financial condition
In the course of the acquisition of the properties, we entered into financing transactions with third parties and affiliates. These financing agreements will require us to pay principal and interest. There are several rules in German tax laws restricting the tax deductibility of interest expenses for corporate income and municipal trade tax purposes. Such rules have been changed considerably on several occasions in recent past. As a result, major uncertainties exist as to the interpretation and application of such rules, which are not yet clarified by the tax authorities and the tax courts. The tax deductibility of interest expenses depends on, among other things, the details of the security structure for debt financings, the annual amount of tax net-debt interest, the amounts and terms of unitholder or affiliate financings and our general tax structure. There is a risk of additional taxes being triggered on the rental income and capital gains in case the tax authorities or the tax courts adopt deviating views on the above. If this were the case, this would result in a higher tax burden and, consequently, could have a material adverse effect on our cash flows, financial condition and results of operations and ability to pay distributions on the Units.
Changes in currency exchange rates could adversely affect our business
Substantially all of our investments and operations are conducted in currencies other than Canadian dollars; however, we pay distributions to Unitholders in Canadian dollars. We also raise funds primarily in Canada from the sale of securities in Canadian dollars and invest such funds indirectly through our subsidiaries in currencies other than Canadian dollars. As a result, fluctuations in such foreign currencies against the Canadian dollar could have a material adverse effect on our financial results, which are denominated and reported in Canadian dollars, and on our ability to pay cash distributions to Unitholders. We have implemented active hedging programs in order to offset the risk of revenue losses and to provide more certainty regarding the payment of distributions to Unitholders if the Canadian dollar increases in value compared to foreign currencies.
Changes in interest rates could adversely affect our cash flows and our ability to pay distributions and make interest payments
When concluding financing agreements or extending such agreements, we depend on our ability to agree on terms for interest payments that will not impair our desired profit and on amortization schedules and that do not restrict our ability to pay distributions. In addition to the variable rate portion of the leaseholds in respect of the properties, we may enter into financing agreements with variable interest rates if the current historical low level of interest rates continues. There is a risk that interest rates will increase, which would result in a significant increase in the amount paid by us and our subsidiaries to service debt, resulting in a decrease in distributions to Unitholders, and could impact the market price of the Units.
We rely on Inovalis SA for management services
We rely on Inovalis SA with respect to the asset management of our properties and the property management of the properties. Consequently, our ability to achieve our investment objectives depends in large part on Inovalis SA and its ability to advise us. This means that our investments are dependent upon Inovalis SA' business contacts, its ability to successfully hire, train, supervise and manage its personnel and its ability to maintain its operating systems. If we were to lose the services provided by Inovalis SA or its key personnel, our investments and growth prospects may decline.
While the Trustees have similar oversight responsibility with respect to the services provided by Inovalis SA pursuant to the management agreement, the services provided by Inovalis SA are not performed by employees of the REIT, but by Inovalis SA directly and through entities to which it may subcontract. On April 10, 2018, the Management Agreement will terminate. In anticipation of the term end of the Management Agreement, the independent members of the Board of Trustees have formed a committee to review alternatives available to the REIT.
Investments in, and profits and cash flows from, properties may be lost in the event of uninsured or underinsured losses to properties or losses from title defects
We carry general liability, umbrella liability and excess liability insurance with limits that are typically obtained for similar real estate portfolios in France and Germany and otherwise acceptable to the Trustees. For the property risks we intend to carry "Multi-Risk" property insurance including but not limited to, natural catastrophic events and loss of rental income insurance (with at least a 12 to 18-month indemnity period). We also carry boiler and machinery insurance covering all boilers, pressure vessels, HVAC systems and equipment breakdown. There are, however, certain types of risks (generally of a catastrophic nature such as from war or nuclear accident) that are uninsurable under any insurance policy. Furthermore there are other risks that are not economically viable to insure at this time. We partially self-insure against terrorism risk for our entire portfolio. We have insurance for earthquake risks, subject to certain policy limits, deductibles and self-insurance arrangements. Should an uninsured or underinsured loss occur, we could lose our investment in, and anticipated profits and cash flows from, one or more of our properties, but we would continue to be obligated to repay any recourse mortgage indebtedness on such properties. We do not carry title insurance on the properties. If a loss occurs resulting from a title defect with respect to a property where there is no title insurance or the loss is in excess of insured limits, we could lose all or part of our investment in, and anticipated profits and cash flows from, such property.
IFRS reporting may result in our consolidated statement of financial position and consolidated statement of earnings being subject to volatility as the fair value of our portfolio changes
The fair value of our properties is dependent upon, among other things, rental income from current leases, assumptions about rental income from future leases reflecting market conditions, expected future cash outflow in respect of such leases, the demand for properties such as the properties, the availability and cost of financing and general economic conditions. A change in one or a combination of these factors, many of which are not controlled by us, may have a material impact to the fair value of our properties. Our chosen accounting policy under IFRS requires that real estate assets be recorded at "fair value" with changes in fair value being recorded in earnings in the period of change. Accordingly, our statement of financial position and our statement of earnings are subject to volatility as the fair value of its real estate portfolio changes and these changes may be material.
Reliance on partnerships
The REIT has a material non-controlling interest in partnerships with several institutional investors. These arrangements create a risk as the business objectives or economic interests of the partner, as in any joint business arrangement, may not be aligned with those of the REIT. The partner may want to make decisions that negatively affect the value of its real estate assets or income of the REIT. Such investments may involve risks not present in investments where a third party is not involved, including the possibility that a partner may have financial difficulties resulting in a negative impact on the investment or be liable for the actions of its third party partner. Although the REIT may not have control over these investments and therefore, may have a limited ability to protect its position, such partnership arrangements contain terms and conditions which, in the opinion of the independent trustees, are commercially reasonable, including without limitation such terms and conditions relating to restrictions on the transfer, acquisition and sale of the REIT's and any joint venturer's interest in the joint venture arrangement, provisions to provide liquidity to the REIT, provisions to limit the liability of the REIT and its Unitholders to third parties and provisions to provide for the participation of the REIT in the management of the joint venture arrangements. The REIT's investment in properties through joint arrangements is subject to the investment guidelines set out in the Declaration of Trust.
Risks Relating to Tax Matters
Taxation of Trusts
The REIT qualifies as a "unit trust" and a "mutual fund trust" for purposes of the Tax Act. There can be no assurance that Canadian federal income tax laws and the administrative policies and assessing practices of the Canadian Revenue Agency ("CRA") respecting mutual fund trusts will not be changed in a manner that adversely affects Unitholders. Should the REIT cease to qualify as a mutual fund trust under the Tax Act, the income tax considerations could be material and adverse for the REIT and Unitholders.
Application of the SIFT Rules
The SIFT Rules apply to a trust that is a "SIFT trust" as defined in the Tax Act. Provided that a trust does not own "non-portfolio property" (as defined in the Tax Act), it will not be subject to the SIFT Rules. Based on the investment restrictions of the REIT, the REIT may not acquire any non-portfolio property and, therefore, is not subject to the SIFT Rules. However, there can be no assurance that the SIFT Rules or the administrative policies or assessing practices of the CRA will not be changed in a manner that adversely affects the REIT and Unitholders.
FAPI
The REIT's "participating percentage" (as defined in the Tax Act) of FAPI earned by CFAs of the REIT must be included in computing the income of the REIT for the fiscal year of the REIT in which the taxation year of such CFA ends, subject to a deduction for grossed-up "foreign accrual tax" as computed in accordance with the Tax Act. The deduction for grossed-up "foreign accrual tax" may not fully offset the FAPI realized by the REIT, thereby increasing the allocation of income to the REIT and, therefore, the allocation of income by the REIT to Unitholders. In addition, as FAPI generally must be computed in accordance with Part I of the Tax Act as though the CFA were a resident of Canada and in Canadian currency (subject to the detailed rules contained in the Tax Act), income or transactions may be taxed differently under foreign tax rules as compared to the FAPI rules and, accordingly, may result in additional income being allocated to Unitholders.
Foreign Currency
For purposes of the Tax Act, the REIT generally is required to compute its Canadian tax results using Canadian currency, including for purposes of computing FAPI earned by CFAs of the REIT. Where an amount that is relevant in computing a taxpayer's Canadian tax results is expressed in a currency other than Canadian currency, such amount must be converted to Canadian currency in accordance with the rules in the Tax Act. As a result, the REIT may realize gains and losses for tax purposes by virtue of the fluctuation of the value of foreign currencies relative to Canadian dollars.
Change of Tax Law
There can be no assurance that Canadian or foreign income tax laws, the judicial interpretation thereof, the terms of any income tax treaty applicable to the REIT or its affiliates or the administrative policies and assessing practices and policies of the CRA, Finance and any foreign tax authority or tax policy agency will not be changed in a manner that adversely affects the REIT, its affiliates or Unitholders.
Non-Residents of Canada
The Tax Act may impose additional withholding or other taxes on distributions made by the REIT to Unitholders who are Non-Residents. These taxes and any reduction thereof under a tax treaty between Canada and another country may change from time to time. In addition, the tax consequences under the Tax Act to Non-Resident may be more adverse than the consequences to other Unitholders.
Taxation of the REIT and the REIT Subsidiaries
Although the REIT and the REIT Subsidiaries have been structured with the objective of maximizing after-tax distributions, taxes (including corporate, withholding, land transfer, and other taxes) in the various jurisdictions in which the REIT invests will reduce the amount of cash available for distribution to the REIT by the REIT Subsidiaries and, therefore, reduce the amount of cash available for distribution by the REIT to Unitholders. No assurance can be given as to the future level of taxation suffered by the REIT or the REIT Subsidiaries. In addition, certain tax positions adopted by the REIT and the REIT Subsidiaries may be challenged by the CRA or a foreign taxing authority. This could materially increase the taxable income of, and taxes payable by, the REIT and the REIT Subsidiaries, and thereby increase taxable income of Unitholders and/or adversely affect the REIT's financial position and cash available for distribution to Unitholders.
The extent to which distributions will be non-taxable in the future will depend in part on the extent to which the REIT Subsidiaries are able to deduct depreciation, interest and other expenses relating to our properties for purposes of the Tax Act. No assurances can be given that the CRA will agree with capital cost allowance claims by the REIT Subsidiaries and that expenses claimed by the REIT and the REIT Subsidiaries are reasonable and deductible.
Qualified Investors
We will endeavor to ensure that the Units continue to be qualified investments for Plans. However, there can be no assurance in this regard. In addition, Redemption Notes or other property received on an in specie redemption of Units may not be qualified investments for Plans. The Tax Act imposes penalties for the acquisition or holding of non-qualified investments.
German Taxes
As described under the heading Certain Non-Canadian Income Tax Considerations – Certain Material German Income, Withholding and Real Estate Transfer Tax Considerations in the IPO final prospectus dated March 28, 2013, the German SPV would be subject to municipal trade tax ("TT") if it acts through a German permanent establishment. We have assumed that the German SPV will not be subject to TT based on our current understanding of the structure. However, no assurances can be given that the German SPV will not be subject to TT.
The German real estate transfer tax (the "RETT") generally applies where there is a transfer of legal title of properties from one legal person to another. If the German SPV exercises the purchase option in respect of the Hanover Property (see Certain Non-Canadian Income Tax Considerations – Certain Material German Income, Withholding and Real Estate Transfer Tax Considerations in the IPO final prospectus dated March 28, 2013), legal title to German real estate would be transferred and, consequently, RETT would be payable in connection therewith.
OUTLOOK
We believe that the current market environment is a favorable one for the REIT to prosper. In addition to actively managing our properties, we are continuously assessing potential acquisitions in our target markets and will focus on the ones offering value and stability. Our long-term credit worthy tenants, low cost of debt with proper maturity and the foreign exchange rate contracts for our distributions until April 2019, not only provide investors with steady cash flows, but also serve as a basis for future growth. In addition of the cash available, we can also sell some portion of assets that we own to get access to additional cash and at the same time diversify our portfolio risk.
CRITICAL ACCOUNTING POLICIES
The preparation of the REIT's audited consolidated financial statements in conformity with IFRS requires management to make judgments and estimates affecting the reported amounts of revenues and investment properties owned directly and indirectly at the reporting date. However, uncertainty about these estimates could result in outcomes requiring a material adjustment to the carrying amount of the asset or liability affected in future periods.
We consider the following policies and estimates to be the most critical in understanding the assumptions and judgments that are involved in preparing our financial statements and the uncertainties that could affect our financial results, financial condition and cash flows: (i) recognition and valuation of investment properties; (ii) distinction between business combinations or asset acquisitions and (iii) classification of and accounting for joint arrangements.
A more detailed description of significant accounting policies and critical accounting judgment and estimates that we apply under IFRS is provided in notes 3 and 4 of the consolidated financial statements as at December 31, 2016.
DISCLOSURE CONTROLS AND PROCEDURES AND INTERNAL CONTROLS OVER FINANCIAL REPORTING
The REIT's Chief Executive Officer (the "CEO"), and the Chief Financial Officer (the "CFO") of the REIT are responsible for establishing and maintaining the REIT's disclosure controls and procedures ("DCP") including adherence to the Disclosure Policy adopted by the Board of Trustees. The Disclosure Policy requires all staff and certain other personnel providing services to the REIT to keep senior management fully apprised of all material information affecting the REIT so that they may evaluate and discuss this information and determine the appropriateness and timing for public release.
The REIT's CEO and the CFO are also responsible for the design of internal controls over financial reporting ("ICFR"). Internal control over financial reporting includes those policies and procedures that (1) pertain to the maintenance of records that, in reasonable detail, accurately and fairly reflect the transactions and disposition of the assets of the REIT, (2) provide reasonable assurance that all transactions are recorded as necessary to permit the preparation of financial statements in accordance with International Financial Reporting Standards, and that receipts and expenditures of the REIT are being made only in accordance with authorizations of the management and Trustees of the REIT, and 3) provide reasonable assurance regarding prevention or timely detection of unauthorized acquisition, use or disposition of the REIT's assets that could have a material effect on the REIT's financial statements.
The CEO and CFO have evaluated the effectiveness of the Company's DCP and ICFR as required by National Instrument 52-109F2 issued by the Canadian Securities Administrators. They have concluded that as of June 30, 2017, the REIT's design and operation of its DCP and ICFR were effective in providing reasonable assurance that material information regarding this report, and the interim consolidated financial statements and other disclosures was made known to them on a timely basis and reported as required and that the financial statements present fairly, in all material aspects, the financial condition, results of operations and cash flows of the REIT as of June 30, 2017.
A control system, no matter how well conceived and operated, can provide only reasonable, and not absolute, assurance that the objectives of the control system are met. As a result of the inherent limitations in all control systems, no evaluation of controls can provide absolute assurance that all control issues, including instances of fraud, if any, have been detected. These inherent limitations include, amongst other items: (i) that Management's assumptions and judgments could ultimately prove to be incorrect under varying conditions and circumstances; or (ii) the impact of isolated errors. Additionally, controls may be circumvented by the unauthorized acts of individuals, by collusion of two or more people, or by Management override. The design of any system of controls is also based, in part, upon certain assumptions about the likelihood of future events, and there can be no assurance that any design will succeed in achieving its stated goals.
SOURCE Inovalis Real Estate Investment Trust

David Giraud, Chief Executive Officer, Inovalis Real Estate Investment Trust, Tel: +33 1 5643 3323, [email protected]; Anne Smolen, Chief Financial Officer, Inovalis Real Estate Investment Trust, Tel: +33 1 5643 3323, [email protected]
Share this article