66% of Homeowners Say Their Home Is Their Largest Asset, Yet Only 27% Include Home Equity in Retirement Planning
New HomeEquity Bank and Ipsos research points to an opportunity for Canadians to take a more comprehensive approach to retirement planning as evolving costs put greater focus on cash flow
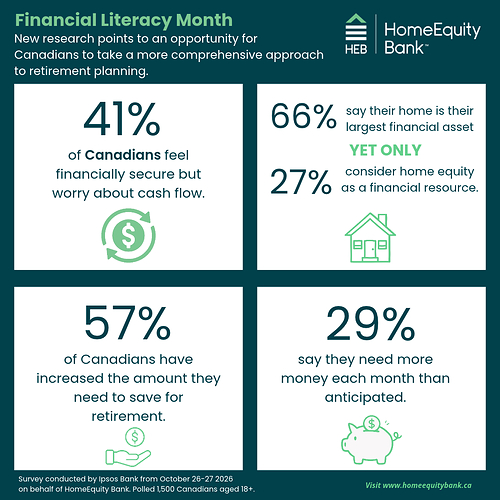
- 66% of homeowners say their home is their largest financial asset, but only 27% consider home equity a retirement resource
- 41% of Canadians feel financially secure overall but worry about having enough readily available cash
- 29% of retirees say they need more money each month than they anticipated
- 35% of Canadians approaching retirement have delayed retirement, while 49% expect to work part-time in retirement
TORONTO, Nov. 18, 2026 /CNW/ -- Canadians have spent decades building wealth, but new research from HomeEquity Bank and Ipsos suggests their retirement plans may not fully reflect all the assets available to them.
Two-thirds (66 per cent) of homeowners say their home is their single largest financial asset, compared with just 8 per cent who point to RRSPs or RRIFs, 6 per cent to workplace pensions and 4 per cent to TFSAs. Yet only 27 per cent of homeowners consider home equity a financial resource that could support them in retirement.
The findings point to an opportunity to broaden the way Canadians think about retirement wealth by considering the home alongside pensions, investments, registered savings and government benefits as part of a comprehensive retirement strategy.
Wealth and cash flow are not the same thing
Canadians can enter retirement with considerable accumulated wealth and still face periods when monthly cash flow does not align with their lifestyle, plans or unexpected expenses.
The research found that 41 per cent of Canadians feel financially secure overall but worry about having enough readily available cash, while 40 per cent are not confident they could manage a major unexpected expense without significantly changing their lifestyle.
Among Canadians approaching retirement, 57 per cent have increased the amount they believe they need to save, 35 per cent have delayed their planned retirement date and 49 per cent expect to work part-time in retirement.
For those already retired, 29 per cent say they need more money each month than they anticipated. More than one-quarter (28 per cent) are drawing more heavily on savings or investments, while 15 per cent are withdrawing more than planned from RRSPs or RRIFs.
"Canadians have done something incredibly important over their working lives: they've built wealth," says Pattie Lovett-Reid, Chief Financial Commentator, HomeEquity Bank. "The opportunity now is to think more broadly about how all of that wealth can support the retirement they want. Retirement planning isn't just about accumulating assets. It's about having the right combination of assets, income and cash flow throughout retirement."
Bringing housing wealth into the retirement plan
Traditional retirement resources remain central to Canadians' plans. Sixty-one per cent of homeowners consider RRSPs or RRIFs retirement resources, 59 per cent point to CPP or QPP benefits and 57 per cent include TFSAs.
But despite the home being the largest financial asset for 66 per cent of homeowners, only 27 per cent currently think of home equity as a retirement resource. That disconnect suggests housing wealth is often considered separately from retirement wealth, rather than as one component of an overall financial plan.
"For most Canadian homeowners, their home represents wealth they have spent a lifetime building," says Yvonne Ziomecki-Fisher, Chief Customer, Brand & Advice Officer, HomeEquity Bank. "A comprehensive retirement plan should consider that wealth alongside pensions, investments, RRSPs, TFSAs and other assets, and how they can work together over time. Home equity won't be the right choice for everyone, but it deserves a place in the retirement planning conversation. For some homeowners, it can provide greater flexibility, strengthen cash flow and help manage unexpected expenses while allowing them to continue living in the home they love."
Planning for a retirement that can span decades
Retirement today can span decades, making the relationship between accumulated wealth and ongoing cash flow increasingly important. Canadians need to consider not only how much they have accumulated when they retire, but how their different assets can work together through changing stages of retirement.
That broader approach can include traditional retirement income and savings as well as housing wealth, particularly for Canadians who plan to remain in their homes and communities as they age.
For eligible homeowners aged 55 and older, a reverse mortgage is one way to incorporate housing wealth into a broader retirement strategy, providing access to a portion of home equity without having to sell the home or make regular mortgage payments.
Your Retirement Wealth and Cash Flow Strategies
With Canadians increasingly concerned about making their money last in retirement, understanding how accumulated wealth can support ongoing cash flow has never been more important. On November 25 at 1 p.m. ET, HomeEquity Bank will host Your Retirement Wealth & Cash Flow Strategies, a webinar exploring the financial realities facing today's retirees and practical strategies to strengthen retirement cash flow, including the role home equity can play alongside other retirement resources. The session is open to mortgage brokers, financial planners and consumers.
To learn more or register, visit https://bit.ly/3Uz5fMk.
About HomeEquity Bank
HomeEquity Bank is a Schedule 1 Canadian Bank offering a range of reverse mortgage solutions including the flagship CHIP Reverse Mortgage™ product. The company was founded in 1986 to address the financial needs of Canadians who wanted to access the equity of their top asset – their home. The Bank is committed to empowering Canadians aged 55 plus to live the retirement they deserve, in the home they love. HomeEquity Bank is a portfolio company of Ontario Teachers' Pension Plan Board, a global investor that delivers retirement income for 340,000 current and retired teachers in Ontario. For more information, visit www.chip.ca.
About the Survey
These are the findings of an Ipsos survey conducted on behalf of HomeEquity Bank that was fielded between October 26-27, 2026. A total of n=1,500 Canadians aged 18+ participated in the survey, including a boost sample of n=500 Canadians aged 55 and older. The survey was conducted using the Ipsos panel. Quotas and weighting were used to ensure the sample's composition reflects that of the Canadian population according to census parameters. This survey has a credibility interval of +/- 2.7 per cent 19 times out of 20, of what the results would have been had all Canadian adults 18+ been surveyed. Credibility intervals are wider among subsets of the population.
SOURCE HomeEquity Bank

Media Contacts: Jack Wilson - [email protected] - (416) 676-1926; Matt Roth - [email protected] - (647) 518-6754
Partager cet article